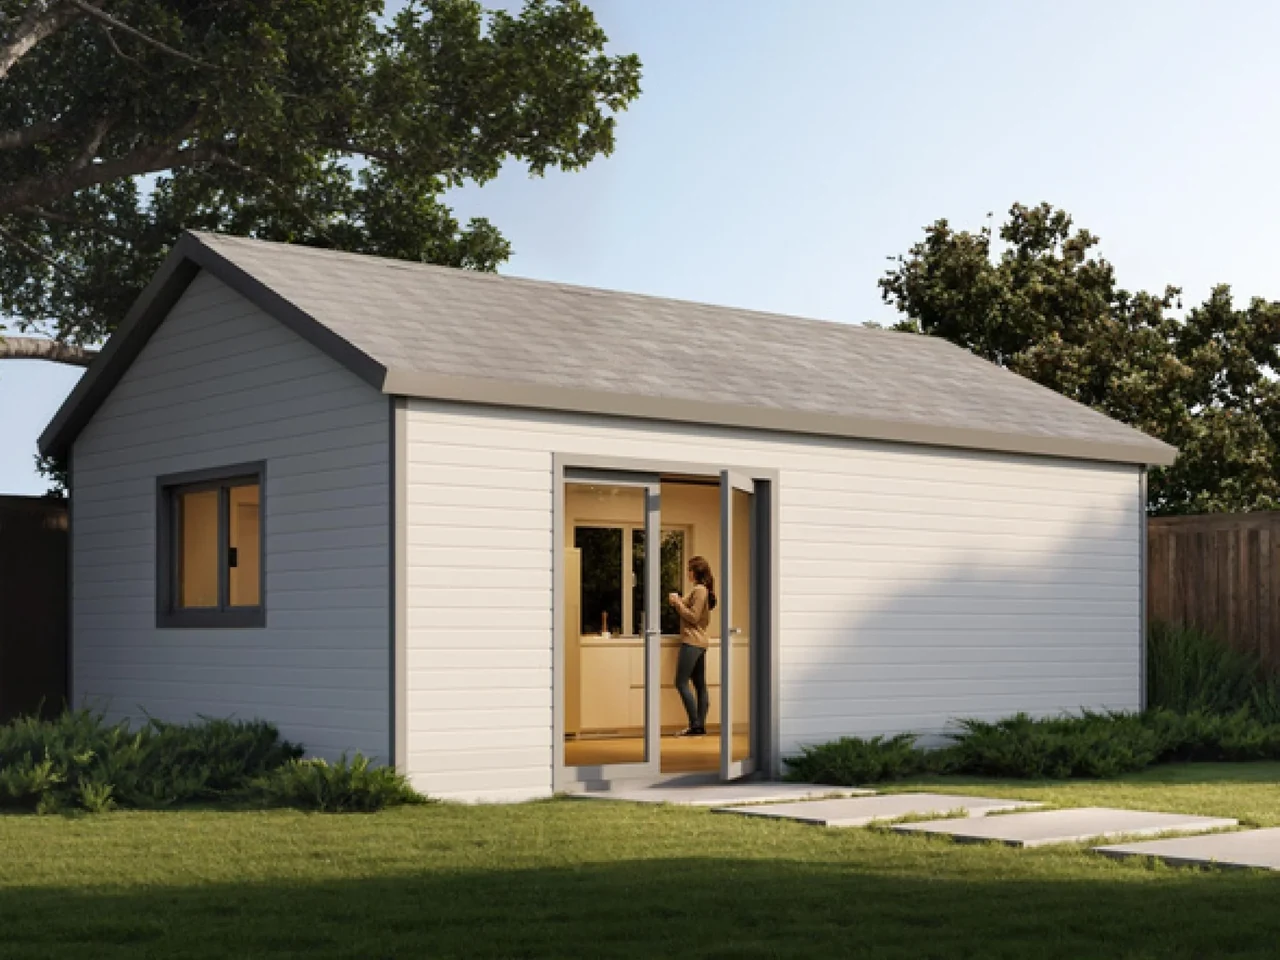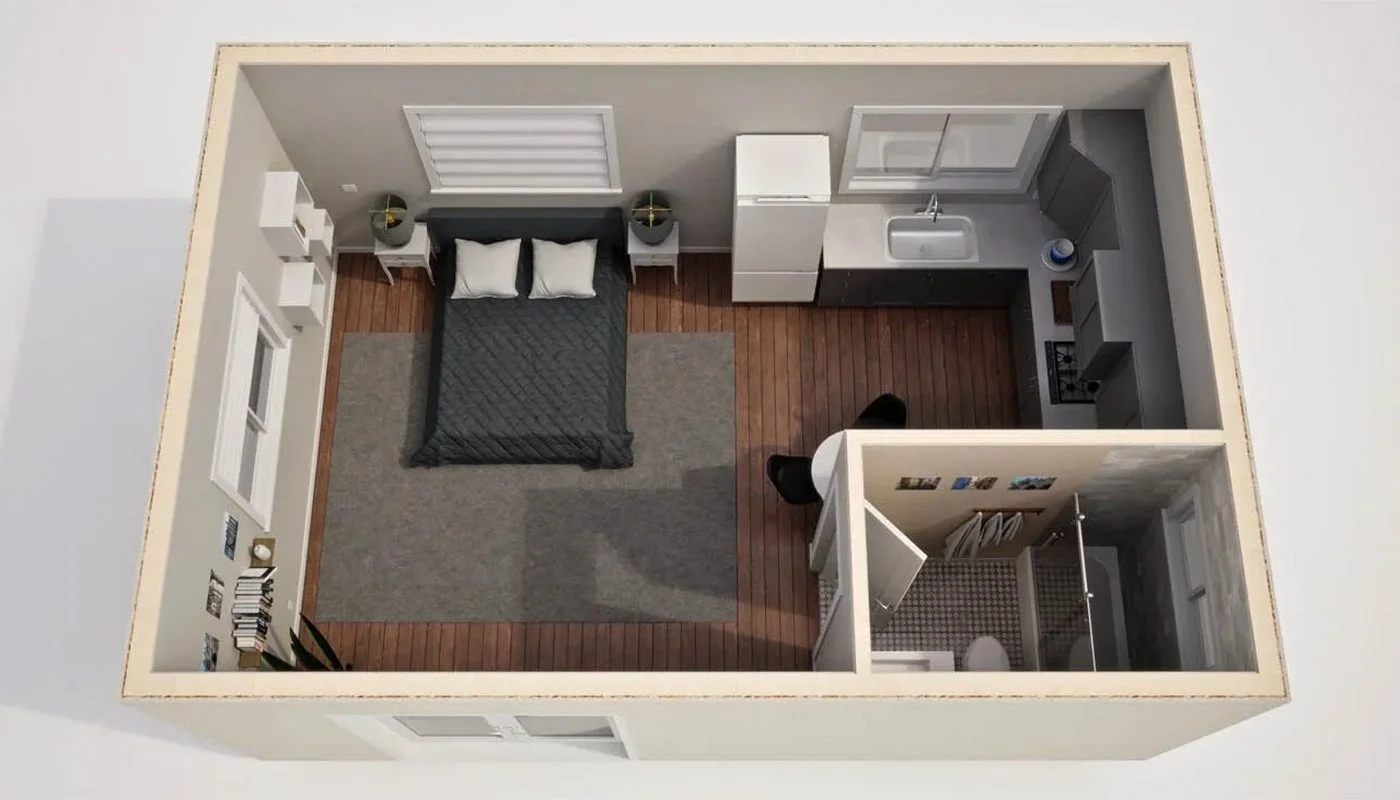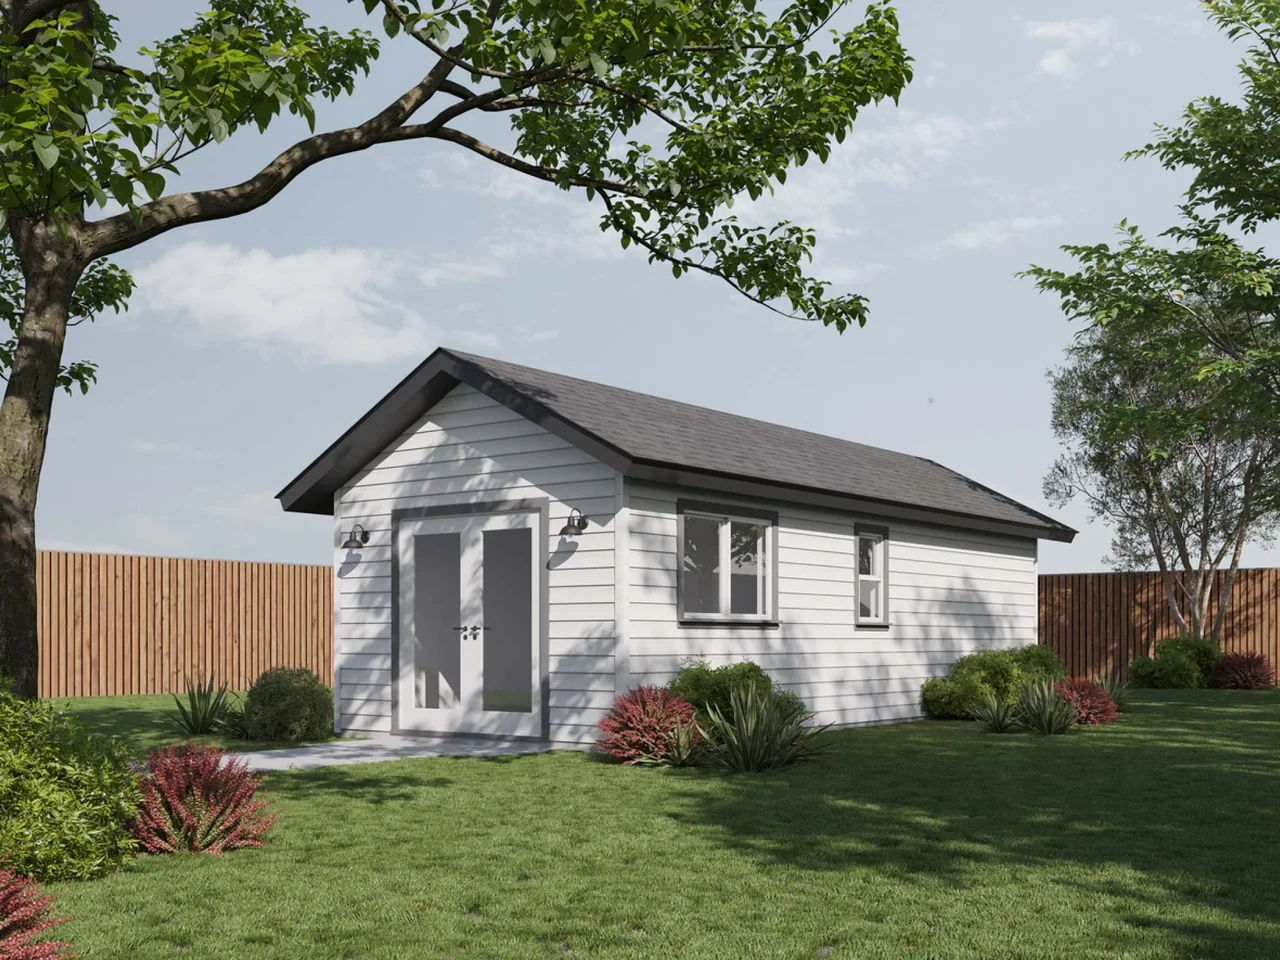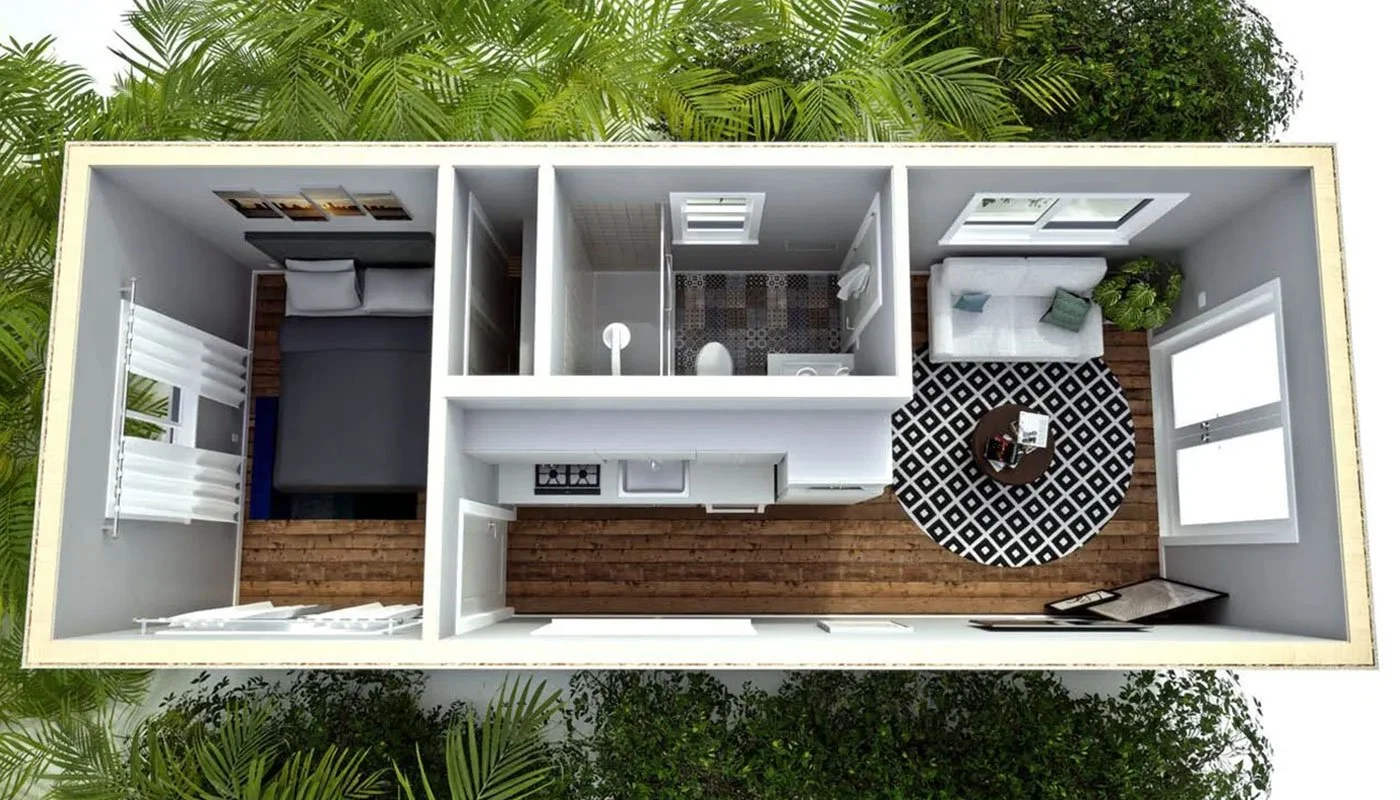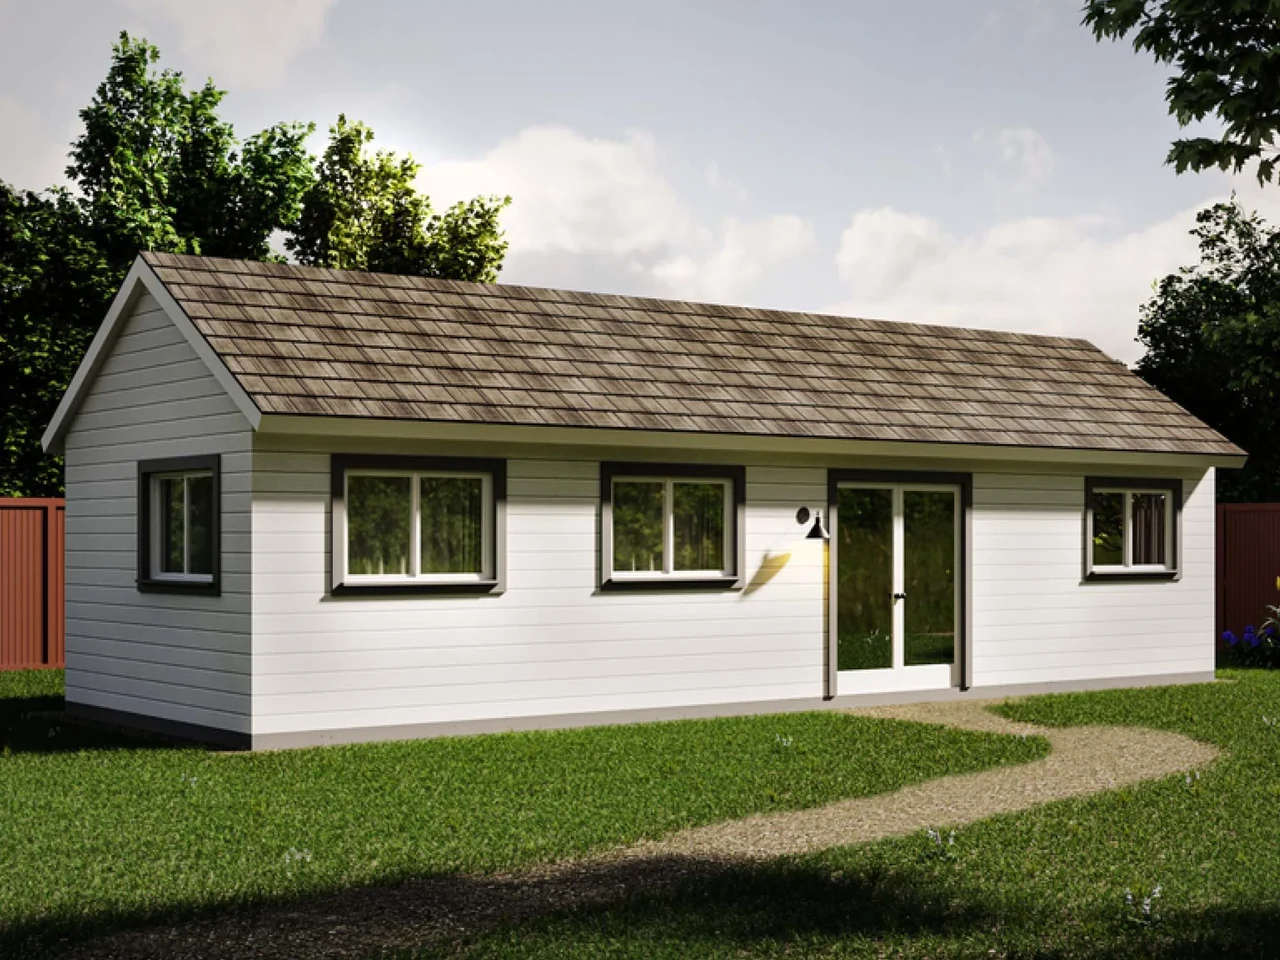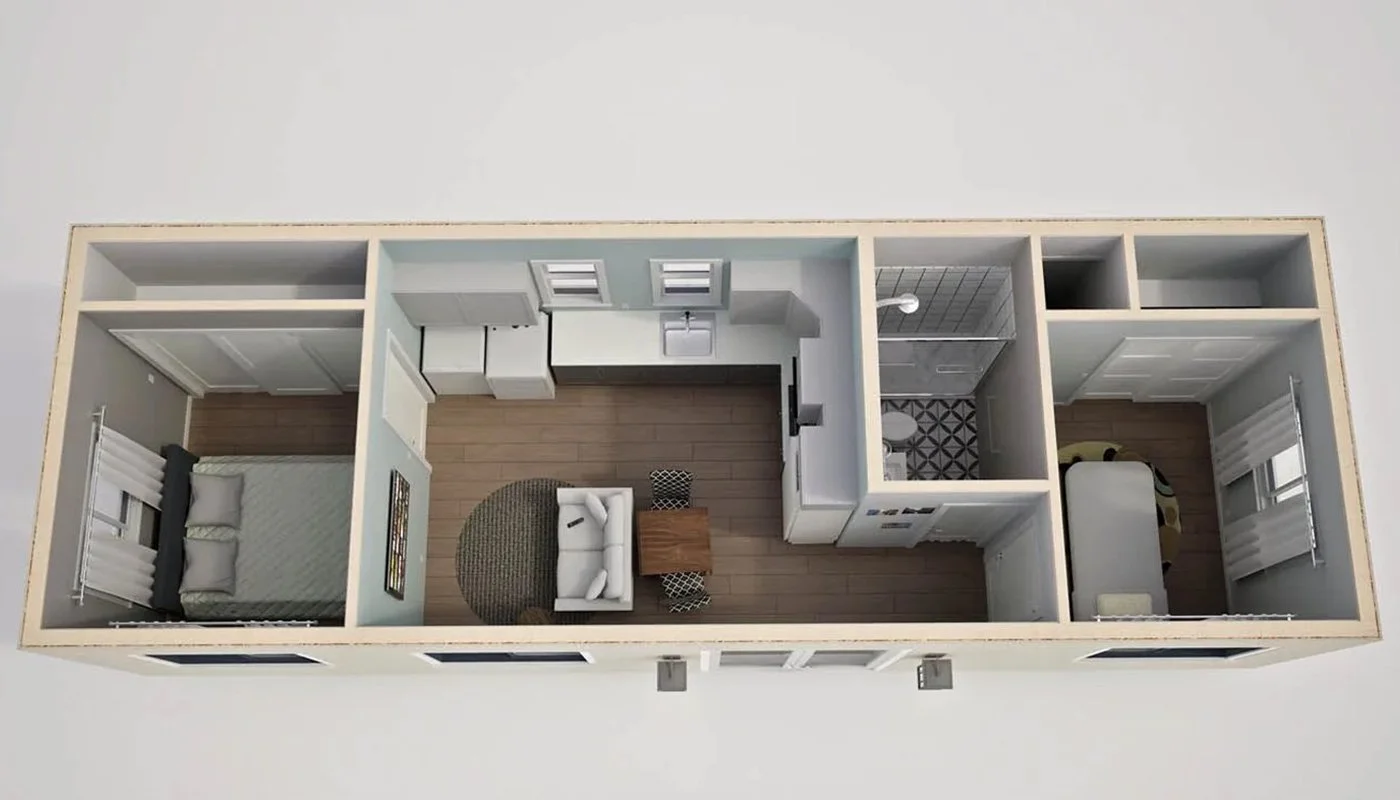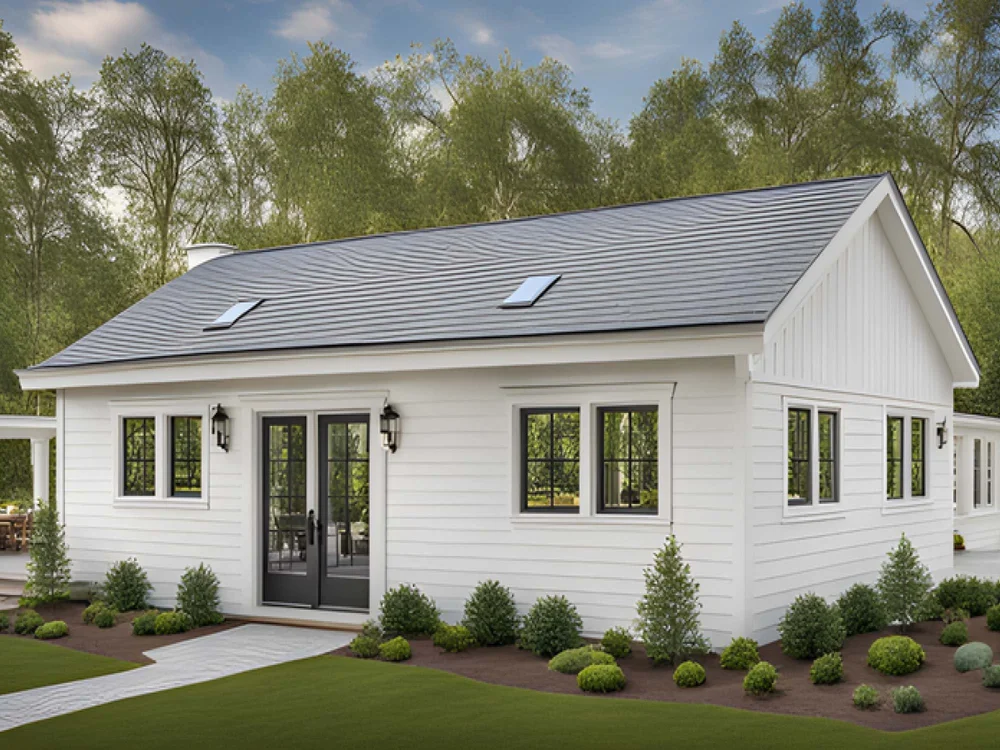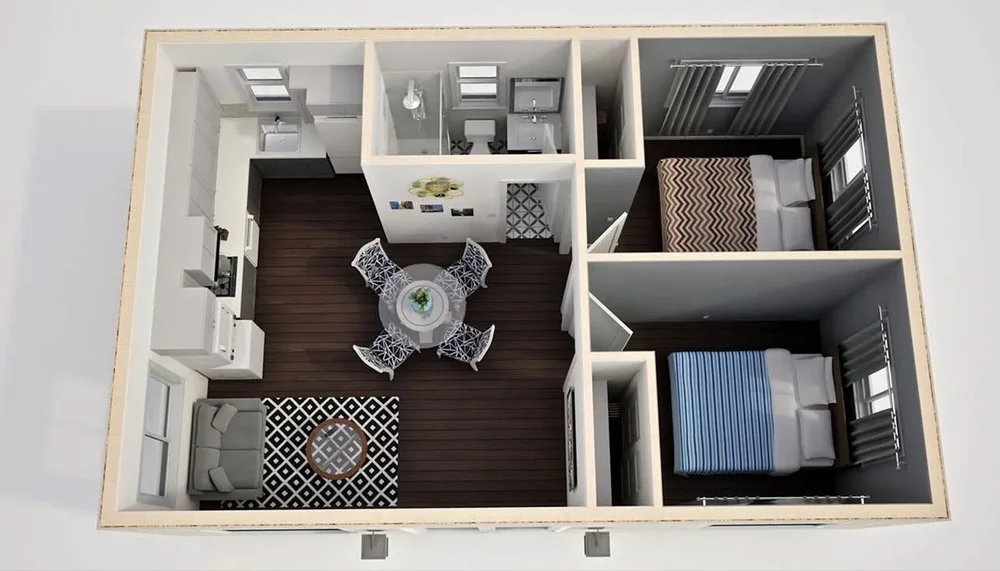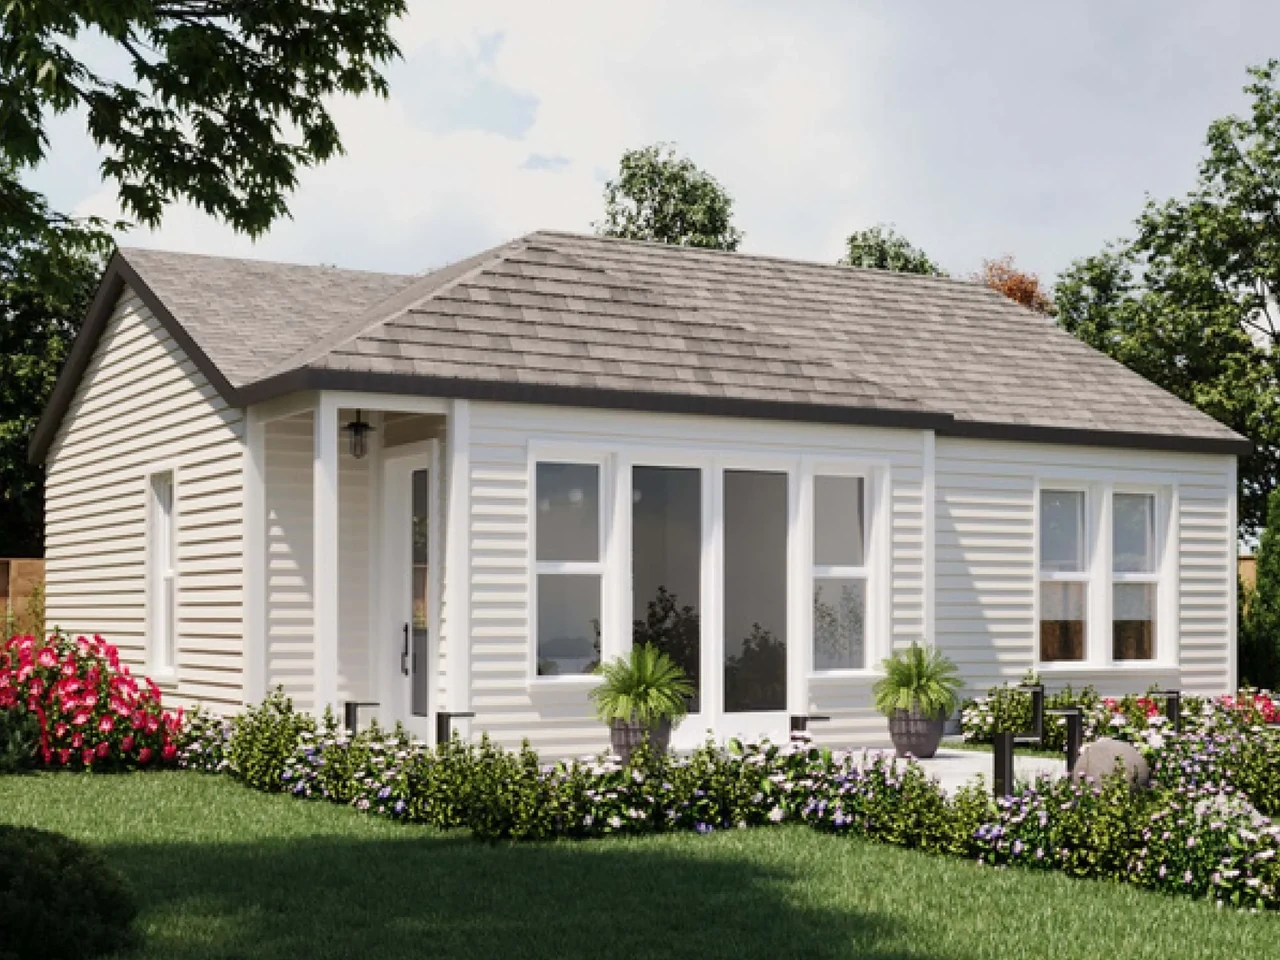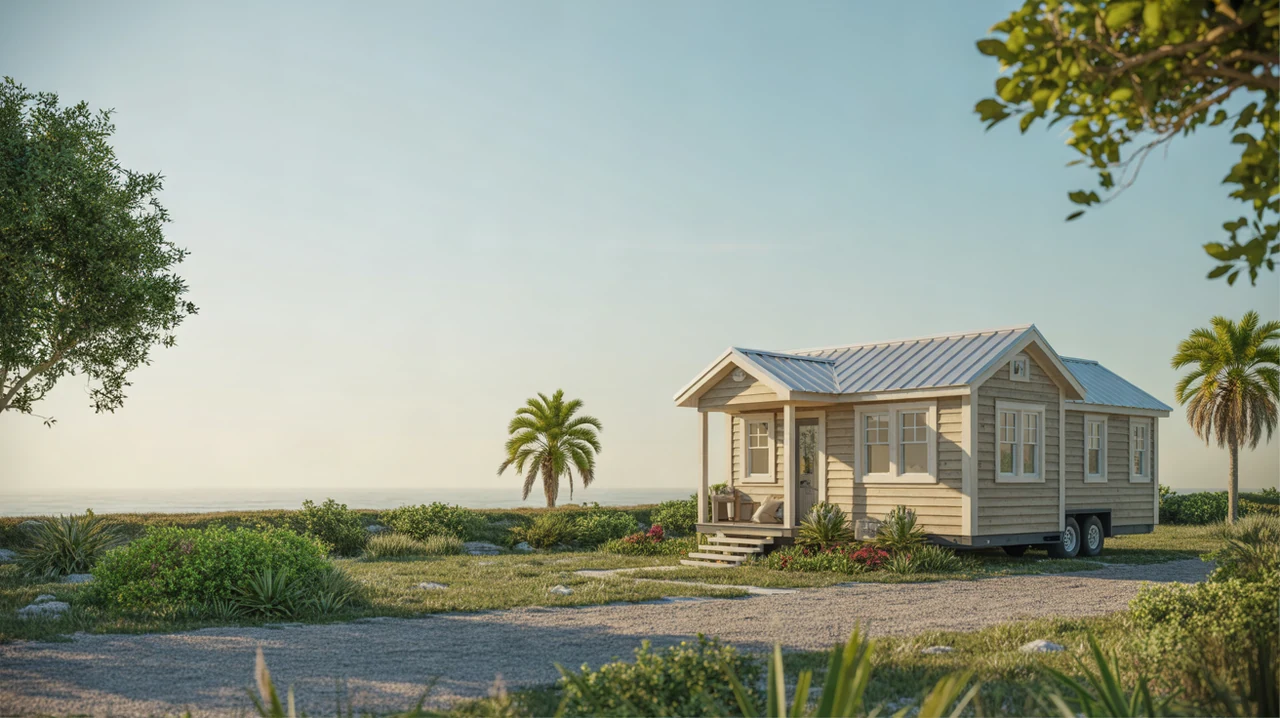
Financing a tiny home near Daytona Beach can feel confusing because these homes don’t always fit neatly into traditional mortgage rules. Whether you want a beach-adjacent tiny house on wheels or a small cottage on a foundation, there are workable ways to pay for it if you understand your options and plan ahead.
First Step: Know What You’re Financing
Lenders look at tiny homes in different ways depending on how they are built, titled, and used. Before you compare loans, get clear on your situation:
- Type of tiny home: on wheels (THOW), park model, manufactured home, or site-built cottage.
- Where it will sit: in a tiny home community, RV park, back yard ADU, or rural land near Daytona Beach.
- How you’ll use it: primary home, vacation place, or rental.
These details determine whether you’re more likely to use an RV-style loan, a construction or mortgage product, or a personal/alternative financing option. For zoning and placement basics, see Tiny Home Zoning, Permits, and Legal Basics.
Can You Get a Traditional Mortgage on a Tiny Home?
Sometimes, but only when the home is treated more like a conventional house than an RV. In the Daytona Beach area, you’re more likely to qualify for a mortgage if:
- The home is built on a permanent foundation.
- It meets local building codes and is considered real property.
- You also own the land (or are buying land and home together).
- The square footage and design meet the lender’s minimum standards.
Types of mortgage-style options
- Conventional mortgage: Best for code-compliant small homes on land. Often has stricter property and appraisal requirements.
- FHA / VA / USDA loans: May be possible for some small homes on a foundation that meet program rules, but very small “tiny houses” often do not qualify.
- Construction-to-permanent loan: Finances the build of a small house on your lot, then converts into a long-term mortgage.
If your goal is a permanent tiny home on a foundation near Daytona Beach, review Tiny Houses on Wheels vs Foundation to see how your choice affects financing.
Financing for Tiny Homes on Wheels and Park Models
Many tiny homes for sale near Daytona Beach are built on trailers. These usually don’t qualify for standard mortgages because they are movable and titled like vehicles, not real estate.
RV and chattel loans
- RV loans: Some lenders finance tiny houses on wheels that meet RV or park model standards. Terms can be similar to travel trailer loans.
- Chattel loans: Loans for movable property (like manufactured homes not attached to land). Rates are often higher than mortgages but lower than many credit cards.
When these work best
- You’re placing the tiny home in a tiny home community or RV park.
- You don’t own land but can lease a pad near Daytona Beach.
- You want the option to relocate the home in the future.
To compare where you might park or place a financed THOW, see Best Tiny Home Communities and Parking Options.
Using Personal Loans for a Tiny Home
Personal loans (sometimes called unsecured loans) are one of the most flexible ways to pay for a tiny home, especially if the purchase price is under $50,000–$75,000.
Pros
- Fast approval and funding compared to mortgages.
- No need to tie the loan to land or to how the tiny home is titled.
- Can be used for a new or used tiny home, DIY build, or upgrades.
Cons
- Higher interest rates than secured loans.
- Shorter terms mean higher monthly payments.
- Approval depends heavily on your credit score and income.
Personal loans can work well if you’re looking at options similar to those in Tiny Homes Under 50k: Budget-Friendly Options.
Builder Financing and Dealer Programs
Some tiny home builders and dealers offer in-house or partner financing. This can be convenient, but it’s important to compare it with outside lenders.
What to watch for
- Interest rate and APR versus local banks or credit unions.
- Hidden fees, documentation charges, and prepayment penalties.
- Whether the loan is secured by the home (and what happens if you can’t pay).
Before committing, review how to evaluate a company’s reputation and contracts using How to Choose a Reputable Tiny Home Builder.
Alternative Ways to Pay for a Tiny Home
If traditional financing isn’t a good fit, there are other paths to consider.
Home equity loans and HELOCs
If you already own a home with equity, you may be able to use a home equity loan or line of credit to buy your tiny home. This can be useful if you’re planning to downsize over time or keep the tiny home as a guest house or rental.
Cash + phased building
- Start with a simpler shell or smaller model you can afford mostly with savings.
- Add features (solar, porches, built-ins) later as your budget allows.
Co-ownership or family financing
In some cases, family or friends help with financing in exchange for future rental use or shared ownership. Make sure you put any agreement in writing and understand local zoning rules, especially if the home will sit on someone else’s property.
Using rental income
Some buyers plan to rent their tiny homes seasonally near Daytona Beach to offset payments. Lenders may or may not count potential rental income in your approval, so don’t rely on it unless it’s built into your loan. To explore this route, read Renting Out Your Tiny Home as a Short-Term Rental.
Comparing Tiny Home Financing Options
| Option | Best For | Typical Term | Key Trade-Off |
|---|---|---|---|
| Mortgage / construction loan | Tiny home on a foundation with land | 15–30 years | Lower rate, but stricter rules and longer process |
| RV / chattel loan | Tiny home on wheels or park model | 5–20 years | More flexible property rules; higher rates than mortgages |
| Personal loan | Smaller or used tiny homes; DIY builds | 2–10 years | Fast approval but higher payments |
| Home equity / HELOC | Current homeowners with equity | 5–20 years | Lower rate, but your main home is collateral |
Practical Steps to Get Ready for Financing
- Clarify your plan
Decide whether you want a movable tiny home or a foundation home, and whether it will be your full-time Daytona Beach residence, vacation spot, or rental. - Estimate your total budget
Include the home, delivery, site prep, utility hookups, insurance, and ongoing costs. Use Tiny Home Prices and Cost Breakdown and Maintenance and Upkeep Costs for Tiny Homes to refine numbers. - Check your credit and debt-to-income ratio
Better credit often means lower interest and more choices. Paying down existing debt can improve your approval odds. - Gather documents
Typical lenders want pay stubs, tax returns, bank statements, and details about the home (builder quote, specs, floor plan). - Get several quotes
Compare local banks, credit unions, online lenders, and any builder financing side by side. Look at total cost over the life of the loan, not just the monthly payment. - Align financing with design
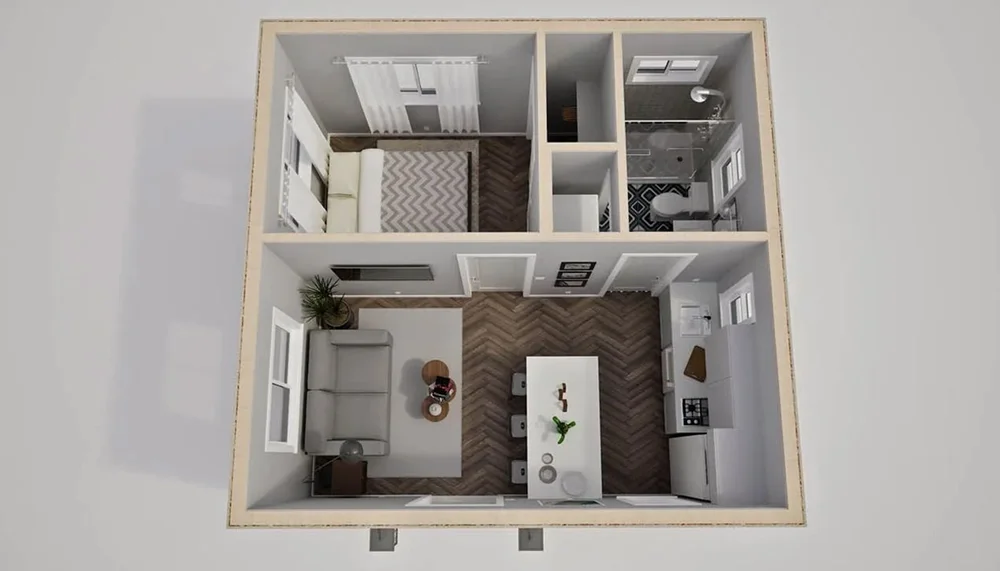
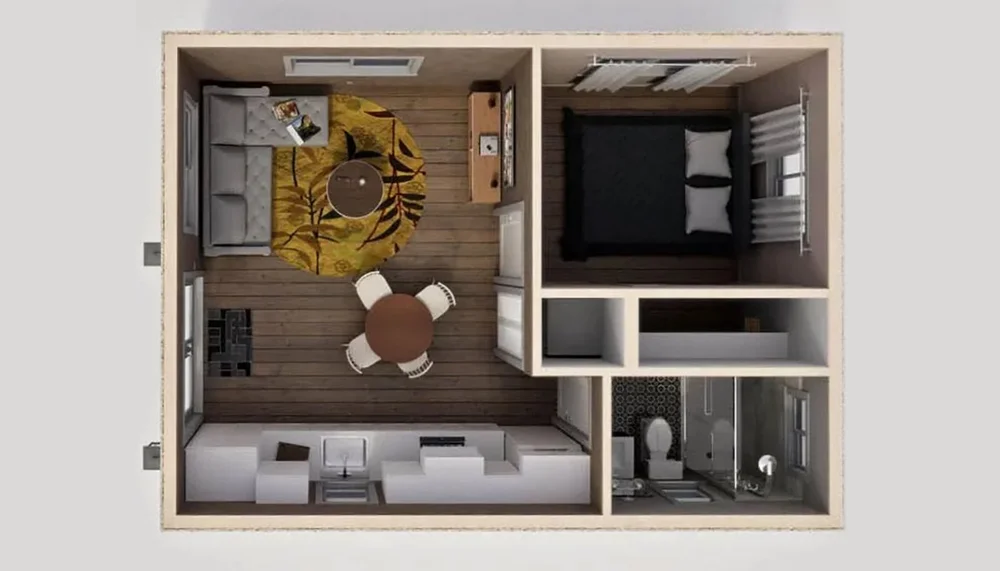
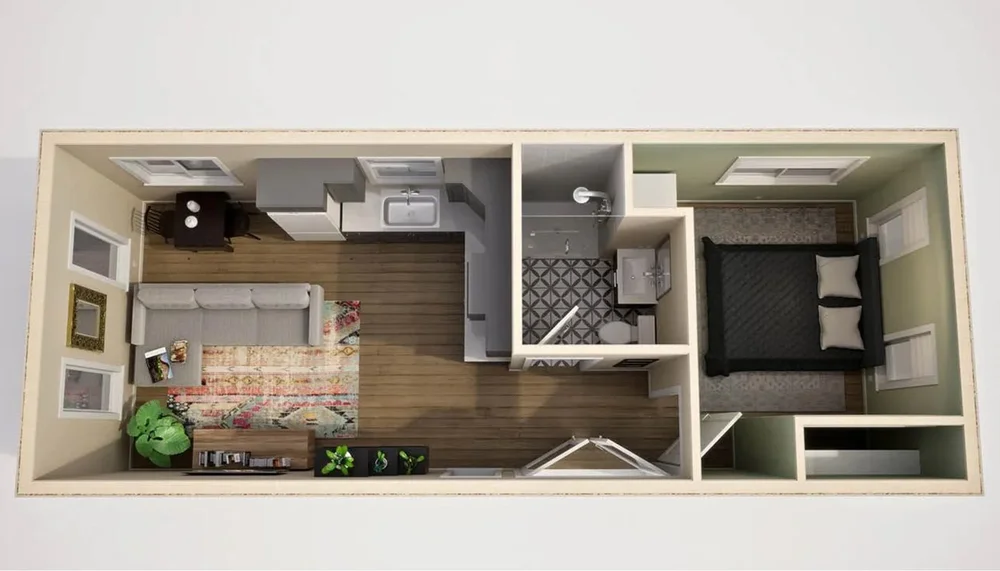
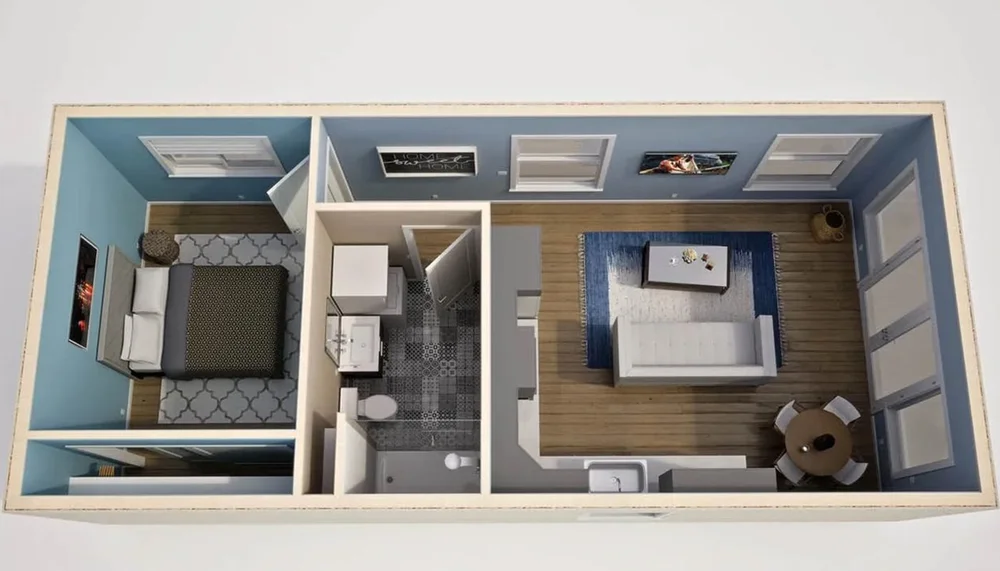
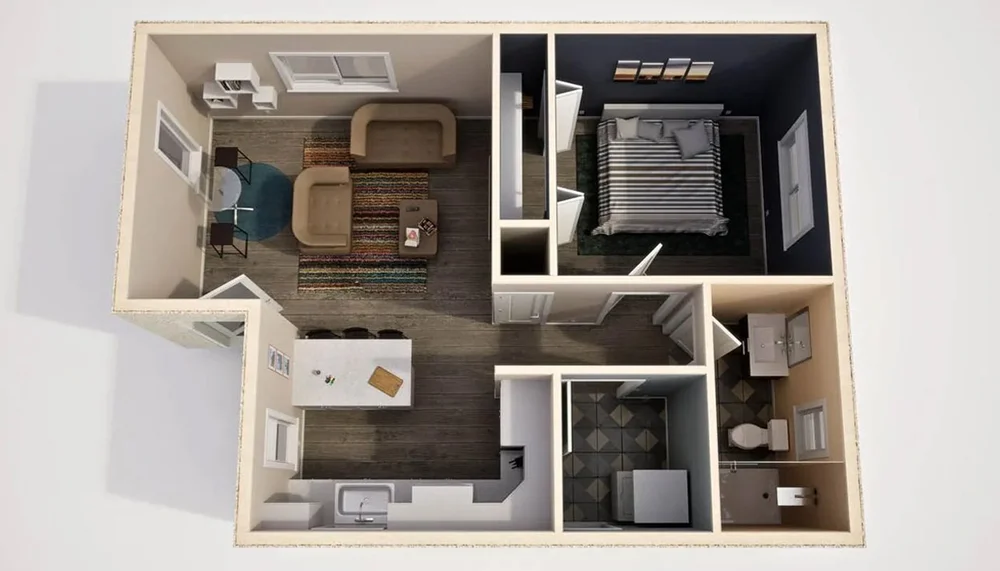
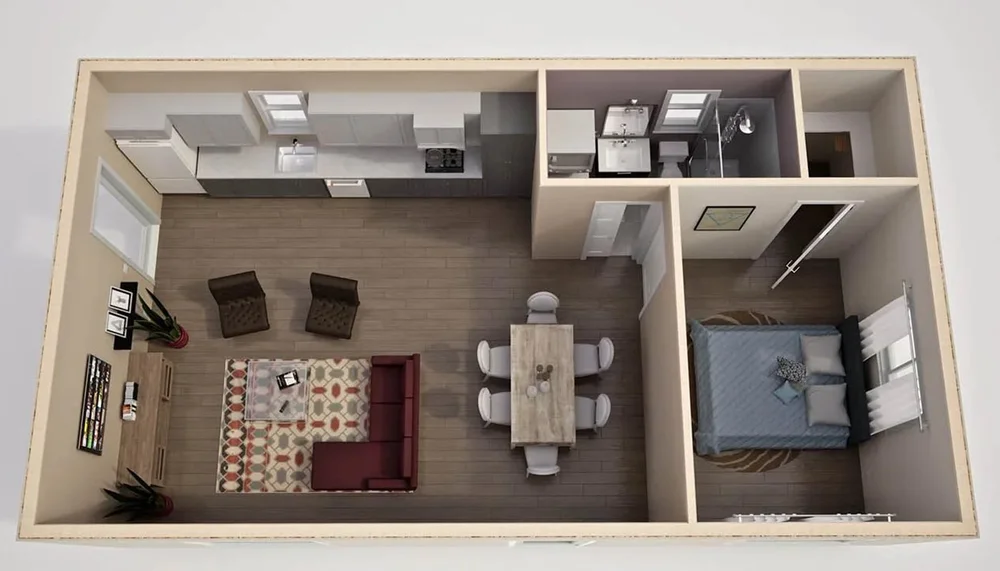
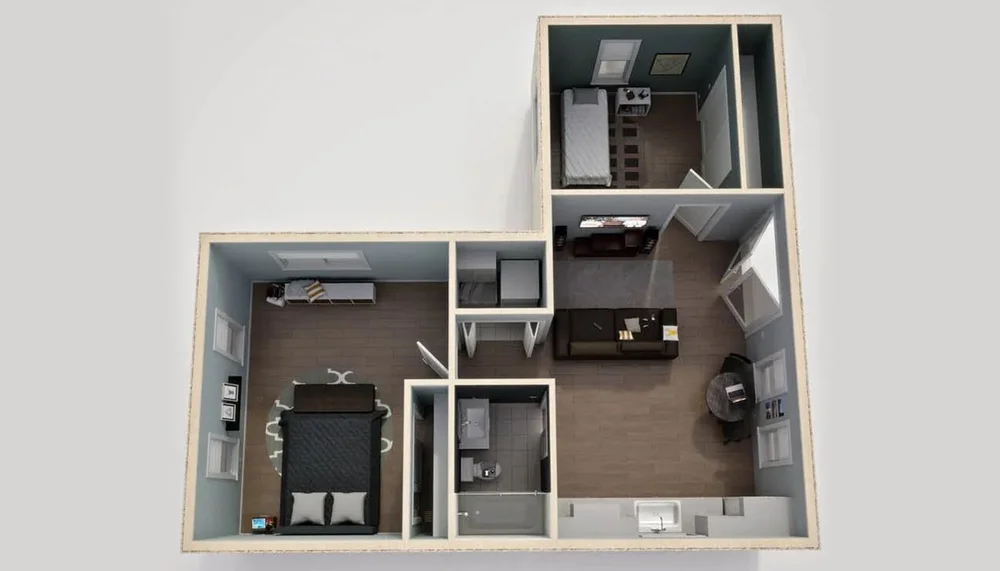
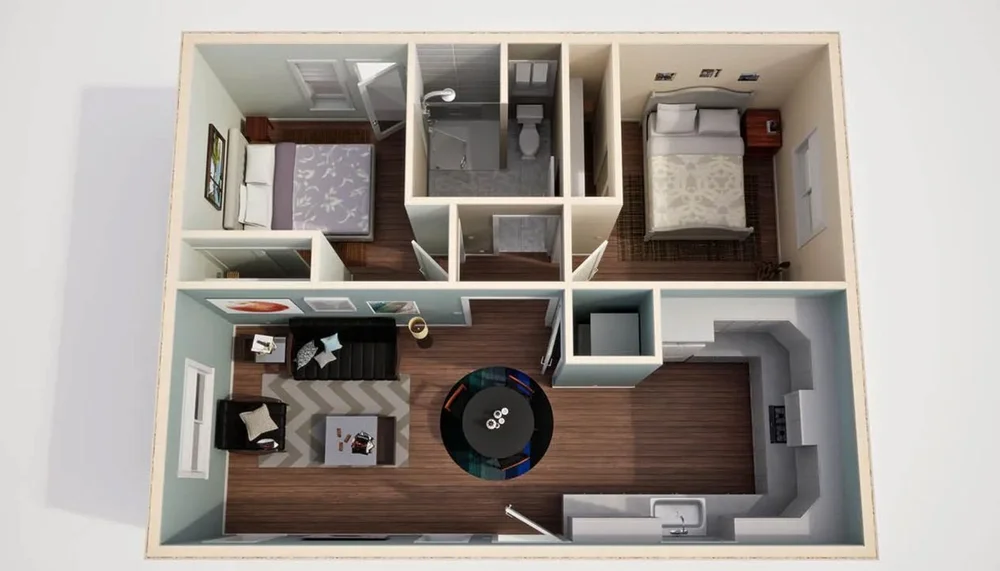
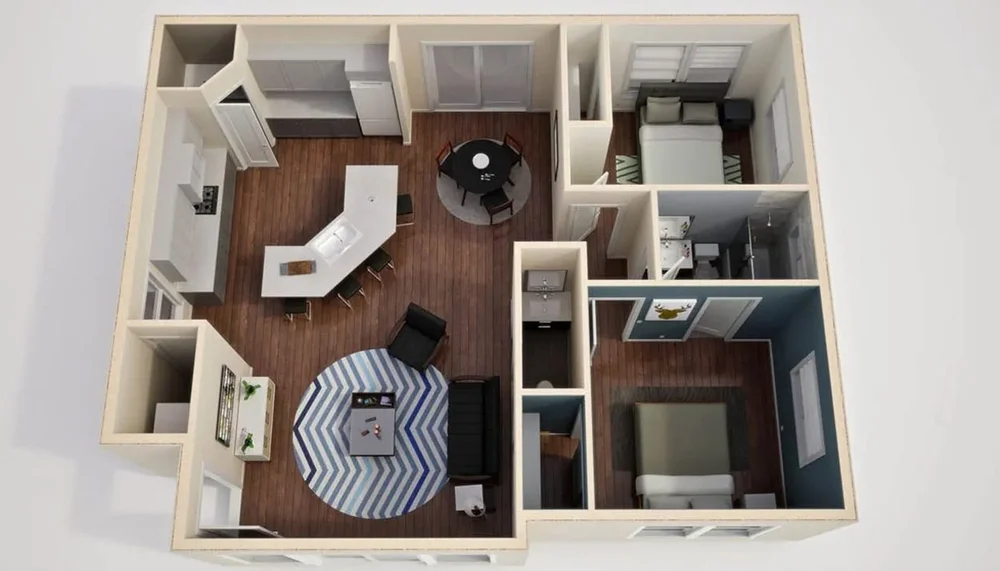
Your budget and loan type may influence size, materials, and features. For ideas on making a smaller footprint work, see Tiny Home Floor Plans and Layout Ideas.
FAQs About Financing Tiny Homes Near Daytona Beach
Is it harder to finance a tiny home than a regular house?
It can be, because many tiny homes don’t meet standard mortgage guidelines. However, by matching your home type to the right loan (mortgage, RV-style loan, or personal loan), most buyers can find an option that works.
How much down payment do I need?
It varies by loan type. Mortgages and construction loans may ask for 3–20% down. RV and chattel loans often want 10–20%. Personal loans might not require a down payment but will base approval on your credit and income.
Can I finance a used tiny home?
Yes, but options may be more limited. Some lenders only finance new units, while others will allow used tiny homes through personal loans or RV-style loans. For pros and cons, see New vs Used Tiny Homes: Pros, Cons, and Pricing.
Will insurance affect my loan?
Most lenders require proof of insurance before funding. The type of policy you need (homeowners, RV, or specialty tiny home coverage) depends on how your home is titled and where it’s parked. Learn more in Tiny Home Insurance and Warranties Explained.
Where can I learn more before I apply?
For a broader overview of buying in this area, visit Tiny Homes for Sale Daytona Beach Buyer’s Guide and our Blog / Guides. When you’re ready to explore specific builders or models, you can also review Custom-Built vs Pre-Built Tiny Homes.